Kristin Beran Krupp · Greater Richmond, Virginia
Homebuyer Guide
Educating you every step of the way.
Every market is different. This guide was designed for today’s market conditions and is applicable no matter how experienced (or inexperienced) you may be in the homebuying process. I will be by your side every step of the way.
Phase 1 · Step 1 of 14
Our first meeting
The shape of the whole thing
Three phases, and the chapter that begins after closing
Every buyer moves through the same three phases. Each one feels different — different pace, different decisions, different worries. Knowing which phase you're in is most of what makes this feel manageable.
Getting started & looking
Representation, pre-approval, criteria, touring. The open-ended phase — could be two weeks, could be six months, and that's fine.
Offers & getting under contract
The exciting, fast-moving phase. Days, sometimes hours. We write strong terms and negotiate — and if one goes to someone else, we simply move to the next with what we learned.
Contract to close
Roughly 30–45 days of steady, well-mapped steps: inspections, loan, appraisal, insurance, utilities, walk-through. Busy, but every date is known in advance.
Post-closing
Records, the first project, the contractor you need on short notice. Long after closing I'm still your resource — this is the part of the relationship I value most.
Getting to know Kristin
My job is to protect your best interests
Every relationship starts with trust. What follows is shared to show you my knowledge base and my dedication to this craft — but none of it matters unless you can place your trust in my ability to represent you well. Being entrusted with something as significant as your home is, to me, the highest form of trust there is.
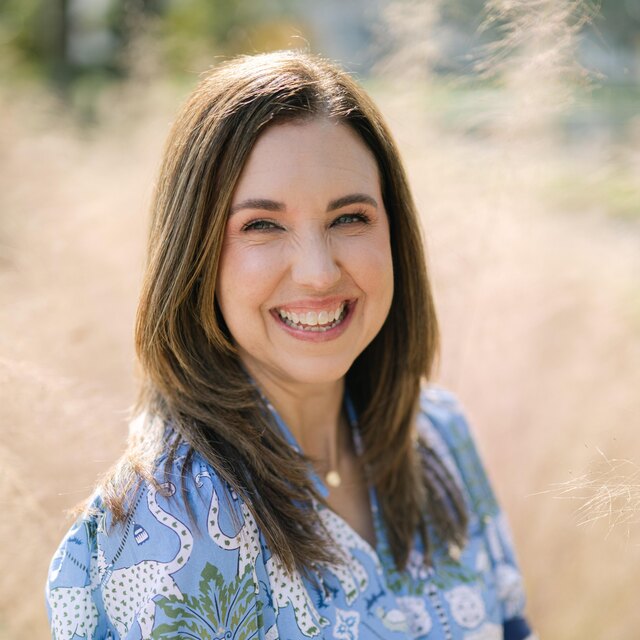
I've been licensed since 2004 and I co-founded The Beran Group, now the number one team at Shaheen, Ruth, Martin & Fonville. Over that career I've been part of more than 1,400 transactions and over $410 million in residential sales, and I'm recognized among the top 1% of Realtors in the country — but what I actually want you to know is that I take the trust you've placed in me very seriously. It never fails to make me pause that someone has placed their housing needs and their dreams with me. I was born and raised in Metro Richmond, and I've spent two decades watching how this region grows and changes.
In 2024 the Richmond Association of REALTORS® named me its REALTOR® of the Year, which remains the professional honor I'm most grateful for. I served as President of RAR and CVR MLS — an association of more than 7,000 members. I've also served as Managing Broker for the largest privately held real estate firm in the country, advised national builders on this market, and helped relocate executives from Altria, Capital One, VCU and other Fortune 500 employers in and out of Richmond.
I mention all of that for one reason: it means I usually know what's coming before it arrives. I'm also a state-licensed real estate instructor, so I teach the material my colleagues are licensed on — and that habit of teaching is exactly how I work with clients. My focus is on educating you and sharing what I know so you can avoid the costly mistakes I've watched other buyers make.
Buying a home is one of the largest financial decisions most people ever make, and it is almost never purely financial. It's a new job, a growing family, a loss, a fresh start. I've sat at a lot of closing tables, and the ones that go well are the ones where the buyer understood what was coming next. That's the whole reason this guide exists.
When I'm not working you'll find me walking Malvern Gardens, reading, traveling, or watching my son Anders play squash, tennis and golf with my husband Bryan.
How I work
You'll always hear the full picture from me early, while there's still time to act on it. If a home has an issue, I'd rather we look at it together than discover it later.
I teach real estate to other agents across the state, and I bring the same approach here: hand you the information and the options so you can avoid an expensive mistake. The decision is always yours.
Losing three offers in a row wears people down. I'd rather spend real time on strategy up front than let you learn the market by getting beaten by it.
Most of my business comes from people I helped years ago. That only works if I'm still useful long after closing, when there's nothing in it for me.
Where the industry is, honestly
Representation and compensation changed for buyers in 2024, and the honest read is that it was overdue. You now sign an agreement that says in writing what I owe you and what I'm paid, before I show you anything. I'd rather have that conversation out loud on day one than have you wonder about it in month three.
Portals and automated estimates are genuinely useful, and they are also confidently wrong about specific houses all the time. The listing photos won't tell you about the drainage. What you're hiring is judgment about the things that aren't in the data.
Richmond has quietly become a place people move to rather than from, which is why supply stays thin even as the frenzy fades. That's the tension you're buying into — a slower market that still moves fast on the good ones.
Your team
Who to call, and for what
You are never obligated to use anyone on this list — shop it, and compare. These are simply the people I've watched perform under pressure for my clients, and who answer the phone. When you're not sure who handles something, call me and I'll route it.
Movement Mortgage
Your pre-approval, your rate lock, and the monthly number you actually live with. Talk to them first — before you look at a single home.
Apply with Casie →Heath Gates · CowanGates
My recommendation, and the choice is entirely yours. Heath’s team runs the title search, clears anything on record, and hosts your closing. Owner’s title insurance protects your ownership for as long as you hold the home.
Towne Insurance
Independent advisors, so they shop multiple carriers for you. Start quotes as soon as you’re under contract — older roofs and flood zones take longer.
(757) 897-9752
Inspectors I trust
Three I recommend, and the choice is yours. Radon, chimney, pool, well and septic are separate specialists I can line up at the same time.
I’ll schedule it for you — seller approves the time
Susan Parsons & Debbie Williamson
In-house, and they keep contract-to-close moving: tracking loan progress, ordering warranties and inspections, coordinating paperwork with the attorney and lender, and sending you the utility contacts.
You’ll hear from them within a few days of ratification
Keith Aldridge · Affordable Locksmith
Rekeying the locks is the first thing I recommend doing after closing — you never know how many copies of a key are out there. Keith is quick, reasonable, and can usually come out the week you move in.
804.350.3255
Cinch or 2-10
A service plan for major systems and appliances. Useful on an older home; it complements homeowners insurance rather than replacing it.
Ask whether it’s worth it for your home
I receive nothing for these referrals. If a vendor ever stops treating my clients well, they come off this list — that’s the whole arrangement.
Phase 1 · Step 2 of 14
Sign your Buyer Brokerage Agreement
Start here
Your Buyer Brokerage Agreement
This is the one piece of paperwork that comes before everything else. In Virginia an agent must have a written agreement with you before showing you homes1,2 — so signing it is simply how we begin.
What it does
Makes you my client rather than a customer. From that moment I owe you loyalty, confidentiality, full disclosure and care1 — and I negotiate for your side, not the seller's.
What's in it
How long we're working together, the area and type of home it covers, and how my compensation works — including what the seller may offer toward it. Every one of those is negotiable, and we read them together.
What it isn't
It isn't a lifetime commitment or an obligation to buy. We can set a short term and keep the scope narrow, then revisit. It's protection for you as much as structure for me.
When can I sign and get started?
Today, if you're ready.
We can sign at our meeting, or I'll send it to you electronically to sign from your phone. Once it's back I turn on your MLS search the same day — including Coming Soon listings, so you know what's about to hit the market before it can be toured.
Who represents whom
Mine. Represents your interests, advises you on price and terms, keeps what you tell me confidential.
Works for the seller. Must be honest with you and disclose known material defects — but owes loyalty to their side.
One agent, both sides, written consent required.3 They go neutral — no advice on terms or negotiation for either of you.
Two different agents from the same firm.4 Each advocates fully for their own client and keeps their information confidential.
One habit worth building now: at an open house or a new-build sales office, say you're represented and give them my name. It keeps your position protected.
If you're considering a new build
Buying or building new construction
I've had the honor of working with some of Richmond's most admired builders over my career, so let me say this plainly first: builders are not the enemy. But representation works differently in a model home than it does at a resale, and almost nobody explains that difference before you walk in.
The person in the model may not be a Realtor
Builders are not required to hire licensed agents to staff their models. The knowledgeable person walking you through options may be a builder employee — not bound by Virginia real estate law, and under no obligation to tell you they aren’t licensed. I’m not suggesting anyone would misrepresent themselves on purpose. They simply aren’t required to say it.
Functionally, it’s a for-sale-by-owner
Working with a builder that way puts you in the same position as buying directly from an owner: the person across the table represents the seller’s interests, on the seller’s contract, on the seller’s terms. Perfectly legal — just know which side of the table you’re on.
Even a licensed builder’s agent can’t represent you exclusively
If the builder does use licensed agents, you still cannot have exclusive representation unless you bring your own. Working with theirs puts you in dual agency — where the agent is neutral and advises neither side on terms — or leaves you simply unrepresented.
It is the more complicated transaction, not the simpler one
New construction has more unknowns than a resale: the builder’s own contract, allowances and change orders, lot premiums, timelines that move, warranty terms, and inspections at stages most buyers don’t know to ask for. Representing a buyer here takes a different skill set, and arguably more of it.
Virginia is a buyer-beware state
The burden of discovery sits on your shoulders, with few exceptions.5 That’s true of a 1920s bungalow and it is just as true of a house that doesn’t exist yet.
The irony worth naming
Many buyers skip representation on a new build hoping to save money — a goal I genuinely respect, because it is exactly what I work toward. Saving you money, and saving you from expensive mistakes, is the job.
Before you visit a model or a sales office: register with my name as your agent on your very first visit, and tell them you’re represented. Many builders will not recognize representation retroactively — one unregistered walk-through can cost you the ability to have me at the table for the whole build. If you’re even thinking about new construction, text me before you go.
Phase 1 · Step 3 of 14
Get pre-approved
Before we write anything
Choose your lender and your loan program first
Not just “I'm pre-approved” — but specifically which lender, and specifically which program: conventional, FHA, VA, VHDA, and at what down payment. Those details go into the contract itself, so we want them settled before we ever write an offer rather than sorted out afterward.
Ask your loan officer to run more than one scenario before you fall in love with a house: the same purchase at 3.5% down versus 5% versus 10%, with the monthly payment and cash to close side by side. Bring me those numbers and we will build your offer around the one that actually fits — then it stays put through closing.
Run your numbers
How much cash will I need?
Move the sliders to picture the cash you'll want available. This is a planning tool, not a quote — your lender's Loan Estimate is the real number, and we'll read it together line by line.
Closing costs are estimated at about 3% of the loan — attorney and lender fees, recording taxes, escrow reserves and prepaid interest. Your lender's figure will be more precise.
Cash to have ready
Estimated for a $450,000 purchase
Your deposit isn't an extra cost — it's credited back to you at closing. Financing $427,500 at today's rates, plan on roughly $2,702 a month before taxes, insurance and any PMI.
Your green file
Documents to gather
Your lender will give you a complete list, but this should serve as a great guide to begin organizing your files needed for financing. Use it as your checklist as you gather them.
You will need to provide proof of funds with your name clearly visible — a recent bank or investment statement works. It goes out with your offer in place of a pre-approval letter.
Protecting your approval
Underwriting re-checks your file right before closing. Until the day you have keys, please don't:
Phase 1 · Step 4 of 14
Choose your locations
Phase one · do your homework
Research any address yourself
Fair housing rules mean I can't rate schools or steer you toward or away from an area10 — so instead, here are the primary sources, the same ones I use. Look anything up on any address before you fall in love with it. Every link opens in a new tab.
How Richmond is mapped: MLS areas
When you see listings described as “Area 22” or “Area 54,” that’s the MLS grid, not a neighborhood name. Central Virginia Regional MLS divides the metro into numbered areas within each locality, and every listing, every comparable sale and every market statistic is filed under one. Knowing yours is genuinely useful: it’s how we compare apples to apples on price, and how I set up your search so you aren’t seeing homes forty minutes from where you want to be.
The counties are large and they are not interchangeable — western Henrico and eastern Henrico are different markets, and so are northern and southern Chesterfield. Our zone map, drawn from the official CVR MLS area map, shows exactly where every numbered zone falls, and it’s worth two minutes with it before we set your search criteria.
Our zone map is based on CVR 1100 (Rev. 03/19), a Central Virginia Regional MLS form.17 Tell me the areas you’re drawn to and I’ll pull sales data for those specific zones rather than the whole metro.
Schools
Check the assigned school for a specific address on the division’s own boundary locator — listing data can be out of date.
Safety
Look at reported activity block by block, and search the state registry by address before you write an offer.
Tax records & property data
Assessed value, tax bill, lot lines, permit history, prior sales. Search “real estate assessment” or “GIS” once you’re on the county site — or ask me and I’ll pull the parcel for you.
Disclosures & older homes
Virginia is largely a buyer-beware state — sellers disclose very little by law.5 Know what that means, especially for anything built before 1978.
Phase 1 · Step 5 of 14
Tour homes
Reading the market together
The four numbers I watch for you
Rather than putting a snapshot here that ages by the week, let me show you what I actually track — and what each number tells us about how to write your offer. I'll bring you current figures for your price range, your county, and your MLS areas whenever we talk, because metro-wide averages rarely describe the home you're competing for.
List price to sales price ratio
What homes actually sell for compared with what they were asking, expressed as a percentage. At 100%, homes are selling right at asking. Above it, buyers are competing; below it, there’s room to negotiate.
Days on market
How long a typical home takes to go under contract. Short means you need to see homes quickly and decide with conviction; longer means you can think overnight.
Months of supply
How many months it would take to sell every home currently listed at the present pace of sales. This is the single best measure of who holds leverage.16
Median and average sale price
The median is the middle sale; the average is affected by the extremes. Watching both, by area and price band, shows where your budget genuinely competes.
Buyer’s market, seller’s market, balanced
Months of supply is the usual dividing line, and it can differ by county and by price band at the very same moment. A $300,000 home and a $900,000 home in the same neighborhood are often in two different markets.
Seller’s market
Fewer homes than buyers. Expect quick decisions, offers at or above asking, and competition on the best listings. Our strategy leans on terms — deposit, timeline, flexibility — so you can win without simply paying the most.
Balanced market
Enough homes for real choice, and enough demand that good ones still move. You can negotiate price and repairs, take an evening to think, and keep every contingency.
Buyer’s market
More homes than buyers. This is where we ask for closing-cost help, repairs, a rate buy-down, or a longer timeline — and where patience genuinely pays you.
Why this matters to you
Knowing in advance whether homes go in a weekend or sit for a month is the difference between feeling prepared and feeling rushed.
The same house warrants a different offer in a 1-month market than in a 7-month market. These numbers decide which levers we pull.
If ratios say homes are going over asking, we shop below the top of your approval so you have room to compete comfortably.
A listing sitting well past its area’s typical days on market is information. Sometimes it’s a problem; often it’s your opportunity.
The question behind the question
“What if I overpay?”
This is perhaps the fear I hear most often, and it’s a completely fair one. It’s also not new — buyers have voiced it in every market since I started in 2004. Here’s the reframe I offer, because it genuinely helps: whether you pay under, at, or above list price is only part of the story.
The real question is never “how did this compare to the list price?” It’s what is this home actually worth in today’s market? List price is one person’s opinion, set before the home ever met a buyer. Market value is what the evidence supports.
A seller underprices a home and you pay 5% over asking. Did you overpay? Very possibly not — you may have simply paid market value for a home that was listed below it.
A seller overprices a home and you buy it for under asking. Did you get a deal? Maybe. Maybe not. “Under list” feels like a win, and sometimes it only means the price started too high.
What we look at instead
Homes genuinely like this one — nearby, similar size and age, sold recently. Closed sales, not asking prices, because only closed sales show what buyers were truly willing to pay.
A new roof, a renovated kitchen, mechanical systems with life left in them. Two homes with identical square footage can be tens of thousands apart on merit alone.
Corner, cul-de-sac, backing to a road, an acre versus a quarter. This is the one thing about a home you can never change later.
Values move over time. In a market with limited supply and steady demand, today’s number often looks reasonable a couple of years on — and how long you plan to stay matters more than most buyers realize.
Before you ever sign an offer, I’ll walk you through the comparable sales for that specific home so you can see the value with your own eyes. You should feel confident about the number because you understand it — not because I told you it was fine.
A useful number, badly used
Price per square foot
It’s an appealing number because it’s simple: divide the price by the square footage and compare. I use it too — as one data point among several. What I’d caution you against is treating it as the deciding factor, because on its own it can lead you away from the right home and toward the wrong one.
Price per square foot is an output of a sale, not the reason for it. Two homes on the same street with identical square footage can be genuinely worth very different amounts — and dividing both prices by the same number hides every reason why.
What the math quietly ignores
A kitchen and a bathroom cost far more per foot to build than a bedroom. A home with more of the expensive rooms carries a higher price per foot for good reason.
As square footage rises, price per foot tends to fall — that’s the normal relationship, not a bargain. Comparing a 4,200-square-foot home to a 1,600-square-foot one on this metric tells you almost nothing.
Basements, attics, bonus rooms over garages, sunrooms and enclosed porches are counted differently depending on the source. Change the denominator and you change the answer.
A renovated kitchen, new mechanicals, real hardwood, a roof with twenty years left — none of it appears in a division problem, and all of it is what you’re actually buying.
An acre on a quiet street versus a quarter-acre facing a main road. Same house, meaningfully different value, and the one thing you can never change later.
Two homes at the same size can live completely differently: a workable floor plan, natural light, ceiling height, storage. Livability doesn’t show up in the metric at all.
How to use it well
It’s most meaningful between homes of similar size, age, style and condition within the same small area — ideally the same subdivision or a few blocks.
A figure far off the local norm is worth investigating. Sometimes it reveals an opportunity; sometimes it reveals a reason. Either way, it prompts a question rather than answering one.
An appraiser doesn’t divide — they select close comparables and make line-item adjustments for size, condition, garage, lot and features. That’s the method worth borrowing.
Recent closed comparables, condition, lot, location, and how long you plan to stay. Price per foot is one line in that analysis, never the summary of it.
If you find yourself ruling out a home you loved because its price per foot looked high, call me before you walk away. Let’s look at the comparables together — the answer is often that the metric was measuring the wrong thing.
Ask me any time and I'll pull these four numbers for your specific search — by county, by MLS area, and by price band. I'd much rather hand you this month's data than have you read last quarter's here.
Phase 2 · Step 6 of 14
Write the offer
Thinking like a seller
Build a strong offer
Price is only one lever. Switch these on to see how the terms change your standing — and what each one actually asks of you. We'll choose the ones that fit your situation, never all of them.
Put down at least 1% of the price — more above $750K. It signals you're serious and that you have cash behind you.
The more you bring, the less financing risk a seller sees. Conventional reads stronger than FHA to most sellers.
Asking the seller to cover closing costs lowers their net. Skipping it makes an equal-price offer worth more to them.
Beat competing offers in set increments up to a maximum, rather than leading with your ceiling.
Keep your inspection and the right to walk, but agree up front not to ask for repairs or credits.
Only raise items above a threshold — say nothing under $500, or you cover the first $3,000.
Match their settlement date, and consider a short rent-back at no charge if they need time.
Let them leave what they don't want, ask for little personal property, skip the home warranty request.
Offer strength
Well suited to a home that's been on the market a while. If we expect company on a weekend, adding a stronger deposit or an escalation clause moves you up a tier.
"I'll pay $2,100 over the highest competing offer, up to $550,000." You beat other offers by increments instead of leading with your ceiling. Where escalations aren't being considered, lead with your highest and best — you may only get one look.
Never wire funds without verifying instructions by phone with your closing attorney at a number you looked up yourself.15 We will never email you wiring instructions.
If you have a home to sell first
Buying with a sale contingency
Most buyers who already own need the equity from their current home to buy the next one. That's completely normal, and it is worth understanding clearly — because a sale contingency is the single term that most affects how a seller reads your offer.
What it actually means
Your purchase depends on your current home selling and closing. If yours doesn't sell within the agreed window, you can exit with your deposit intact. It protects you from owning two homes at once — a genuinely serious risk, and the reason the contingency exists.
Contingent on sale vs. on settlement
These are not the same, and the difference is everything. Contingent on sale means your home isn't under contract yet — the seller is waiting on an unknown. Contingent on settlement means it's already sold and just needs to close. The second is far, far stronger.
How a seller weighs it
Sellers think about certainty, and your offer involves a home they haven't seen and a buyer they won't meet. Against a competing offer with no contingency, many will choose that one even at a slightly lower price — which is exactly why we build the rest of your offer to reassure them. Expect a kick-out clause as well: they may keep marketing and give you a short window to remove the contingency if another offer arrives. It's standard, and it's manageable.
How we make it competitive anyway
The strongest move available to you. List and sell yours, then shop contingent on settlement — you go from a maybe to a near-certainty in the seller's eyes.
Your listing agreement, your ratified contract, your buyer's pre-approval, the inspection already behind you. I present all of it with your offer so the seller can see how solid your side actually is.
A long contingency period is what sellers fear. A tight, realistic timeline — priced correctly on your end so it's achievable — reads as confidence rather than hope.
A larger deposit, no closing-cost credit request, the seller's preferred dates, a rent-back if they need one. Give them reasons to accept the one risk you're asking them to take.
A bridge loan, a HELOC, or a buy-before-you-sell program can remove the contingency entirely. They cost money and don't fit everyone — but ask your lender what's available before you assume you're stuck.
A home that's sat for sixty days, an estate sale, a relocation, a seller who also needs time — these are the situations where your contingency is workable. We aim there rather than at the weekend bidding wars.
The honest sequencing conversation is one we should have early: what your home will realistically sell for, what you'll net, how long it should take, and whether you could carry both for a short period. Those four answers determine your entire strategy — so let's do the math together before we start touring.
Phase 2 · Step 7 of 14
You’re under contract
Ratified
Congratulations — you and the seller have agreed on every term.
Take a breath and enjoy this. Then know that the clock on your timeline started the moment the last signature landed. Every deadline in Phase 3 counts from today, and I’ll walk you through each one in order.
In the next 48 hours
Your earnest money deposit goes in through DepositLink, my transaction team sends the contract to your attorney and lender, and we get your inspection on the calendar.
What changes now
Please don’t change jobs, open credit, or move money without a quick call to me or your lender first. Your approval is being re-verified right up to closing.
Who you’ll hear from
Susan and Debbie, my transaction coordinators, will email within a few days. Your attorney’s paralegal and your loan officer will reach out too. If you’re ever unsure who to answer, forward it to me.
Phase 3 · Step 8 of 14
Deposit, attorney & first deadlines
Phase three · you're under contract
Congratulations. Here's exactly what happens next.
This stage runs on deadlines and contingencies, which is precisely why it's written down. We'll work through it together at ratification — the teal boxes are the things I'll need from you.
Transaction coordinators
Susan Parsons and Debbie Williamson work side by side with me in-house. You'll hear from them by email within a few days — reach them any time at transactions@srmfre.com. My team sends a copy of your contract to your attorney and your lender on your behalf, so you don't have to.
Your attorney of choice
You choose who handles your side of closing, and this decision is time-sensitive — your contract has to go to them right away so they can start title work. You'll receive an engagement letter by email or mail; it matters and it's timely, so call me if anything in it is unclear. If you don't have a preference, I recommend Heath Gates at CowanGates. Once you decide, my transaction team sends your contract to their office and the assigned paralegal will email you directly to get started.
HOA documents
If the property is in an association, the seller orders the documents. Once you receive them you have three days to accept them, ask the seller in writing to bring the home into compliance, or reject them and exit the contract. After those three days the contingency is gone — so I'll email and text you the moment they arrive.
Earnest money deposit
Time is of the essence: we're under tight contractual guidelines to get this into the brokerage escrow account. Send it online through DepositLink — instructions are in the next section — or write a check payable to Shaheen, Ruth, Martin & Fonville Real Estate and drop it at one of my offices.
Phase three · the day your offer is accepted
Pay your earnest money online
Our firm uses DepositLink, so you never have to wire funds, write a check, or drive anything downtown. It is bank-level encrypted with two-factor authentication, and DepositLink does not store your banking details. This is also your protection against wire fraud — if anyone ever emails you wiring instructions for your deposit, it is not us.
Go to srmfre.com, search my name, and open the DepositLink tab — or use the direct link on this page.
Enter the address. If it doesn’t come up, use Manual Entry, then Continue.
Name and address, then a memo — write “Earnest Money Deposit” — and the exact deposit amount shown on your ratified contract.
Choose Connect Instantly, sign in with your bank credentials, and verify by phone or email. Pick the account you want to send from.
Check the amount and the property one more time, then send. Download the PDF receipt and keep it with your closing documents.
What to expect
Shaheen, Ruth, Martin & Fonville Real Estate · 5808 Grove Avenue, Richmond, VA 23226 · 804.288.2100
Phase 3 · Step 9 of 14
Inspections
Inside your inspection window
Look closely now, while you still have every option
You choose the inspector, I schedule it, and we attend together. Anything you ask the seller to address has to be in writing, with a cost to cure, inside the window your contract sets — so let’s book it early.
Property survey
A survey is not required to buy a home — your attorney can speak to whether you want one. What I can tell you as a Realtor is that fences, driveways, trees and GIS maps do not establish property lines; only a survey does. One disclosure you are entitled to: Kristin Beran Krupp, Managing Partner of The Beran Group, is married to Bryan Krupp, Principal Owner of James River Surveying. Bryan Krupp owns 50% of the company, and you are under no obligation to use them — the full written disclosure, including their fee schedule, is at the bottom of this section. Your closing attorney will send more information about surveys generally.
Home inspection
You choose your inspector — I recommend Burgess Inspections, US Inspect, or Chris Bernhardt, who typically travels as far as Chesterfield — and I'll gladly schedule it for you — the date and time need seller approval. Plan on two to three hours, and plan to be there. Anything you ask the seller to address must come with a cost to cure from the inspector or a licensed contractor; you cannot ask the seller to perform inspections. Any secondary inspections — roof, HVAC, electrical, plumbing, structural engineer, irrigation — have to happen inside the same window.
Termite, well & septic
The seller has contractually agreed to a termite inspection within 90 days of closing, and — where applicable — a well water test and a septic inspection and pumping. These are on their side, not yours.
Affiliated business arrangement disclosure · rev. 9/18/2023
James River Surveying, LLC
This is to give you notice that Kristin Krupp with The Beran Group is married to Bryan Krupp, who has a business relationship with James River Surveying, LLC, a land surveying company. Bryan Krupp owns 50% of James River Surveying. Because of this relationship, this referral may provide Kristin Krupp a financial or other benefit.
You are NOT required to use the listed provider as a condition of your purchase, sale, or refinance of the subject property. There are frequently other settlement service providers available with similar services.14 You are free to shop around to determine that you are receiving the best services and the best rate for these services.
A signed acknowledgment of this disclosure is part of your paperwork — I’ll provide the form with your property address for signature. Nothing here obligates you to use James River Surveying, and a survey itself is not required to buy a home.
Phase 3 · Step 10 of 14
Mortgage & appraisal
Your lender’s clock
Application within 7 days, appraisal ordered within 15
From here the loan runs on the contract’s deadlines. Answer every request the same day and this phase stays calm.
Lender
You have the right to choose your own lender. I'm happy to refer people I've worked with, and you're free to use anyone. If your contract is contingent on financing, you must make loan application within 7 days per the contract.
Appraisal
If your contract is contingent on an appraisal, your lender must order it within 15 days of ratification — ordered, not completed. They'll contact you for the fee and scheduling, and the appraiser contacts the listing agent directly, which means I'm often the last to know it's done. That matters: if the home appraises below the contract price you have a limited number of days to ask the seller in writing to reduce, and missing that window waives the right.
Phase 3 · Step 11 of 14
Homeowners insurance
Before closing
Bind your policy, and shop it
Your lender needs proof of insurance before closing. Start quotes now — older roofs and flood zones can take a little longer to place. Towne Insurance, in Your Team, shops several carriers for you.
Homeowners insurance & personal property
You'll need to bind homeowners insurance before closing as part of your loan — ask me for a referral. Note here what personal property your contract says conveys with the home, so there's no confusion at the walk-through.
Phase 3 · Step 12 of 14
Transfer utilities
Phase three · about a week out
Utilities & change of address
Set everything to start on your closing date, so the lights are on the moment the home is yours. Water and sewer are billed by your county or city, so which office you call depends on where you land — every one of them is linked below.
Electric & gas
Dominion covers nearly all of the metro for power. Gas depends on your locality — check your county, or ask me.
Water, sewer & trash
Billed by your locality. Set this up the same day you do power — some counties need a few business days.
Internet & TV
Schedule installation the week you close — appointments book out, and working from home on a hotspot gets old fast.
Make it official
The easy-to-forget housekeeping. USPS forwarding takes a few days to begin, so file it before moving week.
Utilities
The coordinators will send you the contacts. Transfer everything effective your closing date, and don't leave it to the last minute — late transfers cause a real interruption in service, and a house without power can't pass a walk-through.
Phase 3 · Step 13 of 14
Walk-through & closing day
Phase three · the finish line
The day of closing
This is the day everything you've worked toward comes together. It's a calm, straightforward appointment — and knowing exactly how it flows is what lets you enjoy it.
Bring a photo ID
Unexpired and government-issued, for everyone signing. The attorney needs it to notarize, so it's the one thing worth setting by the door the night before.
Your funds, not a personal check
A cashier's check, or wired to the closing attorney. A personal check will not be accepted. If you wire, call the attorney at a number you looked up yourself to verify instructions first — always.
You may not meet the seller
Sellers usually sign separately, often a day or two earlier. That's simply how closings are scheduled here, and it means your appointment is shorter and entirely about you.
We walk the home first
Usually the morning of, or the day before. The walk-through answers one friendly question: is the home in the same condition it was the day we wrote the offer, with any negotiated repairs complete? It isn't a second inspection, and the agreed standard is broom-swept rather than professionally cleaned — so I'd plan a cleaning as your first happy act of ownership.
You get keys at closing
Once everything is signed and funded, the keys are placed in your hand. That's the moment we've been working toward, and I'll be right there with you for it whenever scheduling allows.
HOA passes come later
Pool passes, gate remotes and amenity cards are issued by the association rather than at the closing table, and they can take days or a couple of weeks. Let's request them early so your first summer there starts on time.
Your exact figures often arrive the day of closing, which is completely normal — just ask your lender when to expect them. And if you can, give yourself a day between closing and the moving truck. A little breathing room makes the whole day more enjoyable.
Final walk-through
Usually the day before closing or that morning. The standard is that the home is in the same condition it was in the day the contract was written, and "broom swept" — not professionally cleaned. The seller is also not required to paint or patch walls where artwork hung. I'd rather you know that now than be surprised. If significant repairs were negotiated, we'll walk it a little earlier.
Closing
I'll be there with you unless scheduling makes it impossible. Bring a photo ID and your funds — a cashier's check, or wired to the closing attorney. Ask your lender when to expect exact figures; it is not unusual for them to arrive the day of closing. That's normal, not a problem.
Movers & moving in
Book movers as early as you can — good ones fill up. If at all possible, don't move the same day you close, because delays happen. I also recommend having the home professionally cleaned before you move in, and changing the locks.
Phase 4 · Step 14 of 14
Your first year
After closing
Your first year, and every year after
You have the keys. Here's what to take care of in the first month, what to keep for the long run, and what you can safely set aside. This is the section I hope you come back to for years.
First 30 days
Keep these forever
Call me for
A word about mail you'll get. Within weeks you'll receive official-looking offers to sell you a copy of your deed, a “home warranty” you never asked for, or mortgage-protection insurance. Most of it is unnecessary. Forward anything you're unsure about and I'll tell you honestly whether it's worth your money.
Plain English
Glossary
The words that come up in emails and paperwork. Nobody expects you to arrive knowing these.
A licensed appraiser's opinion of value, ordered by your lender to confirm the home is worth what you're borrowing against it.
A condition that must be met for the contract to proceed — commonly financing, appraisal, or inspection. Your escape hatches.
Good-faith money held in escrow when your offer is accepted. It's credited to your costs at closing, not an extra expense.
A neutral third party holding money or documents until conditions are met. Also the account that collects your taxes and insurance.
A standardized three-page form from your lender showing rate, payment, and closing costs. Compare lenders with it.11
The final numbers, delivered at least three business days before closing. Read it against your Loan Estimate — I'll help.12
Private mortgage insurance, required on most conventional loans under 20% down. It protects the lender, not you, and can come off later.13
Pre-qualified is a conversation. Pre-approved means a lender verified your documents. Only the second one competes.
Both parties have signed and agreed to every term. This is the moment your timeline officially begins.
The seller stays in the home briefly after closing. A powerful, low-cost concession when they need time to move.
The signing appointment where title transfers and you get keys. In Virginia an attorney or title company handles it.
Protects your ownership against defects in the property's history — old liens, errors, unknown heirs. Buy the owner's policy.
Your lender freezes your interest rate for a set window, usually 30–60 days, so a market move doesn't change your payment.
An addendum that raises your price in increments to beat competing offers, up to a maximum you set.
A property publicly marketed before it can be shown. You can see it and plan for it, but showings don't begin until it goes active — so it's your early warning about what's arriving.
Your final look before closing, confirming condition and completed repairs. Not a second inspection.
Prepaid interest — 1 point is 1% of the loan — to buy your rate down. Worth it only if you'll hold the loan long enough.
Money the seller credits toward your closing costs. Helpful for cash-tight buyers, but it weakens a competitive offer.
No matching term — ask me and I’ll explain it.
Check my work
Sources and further reading
Every superscript number in this guide points here. These are primary sources — Virginia statute, federal regulation, and the associations that produce the market data — so you can verify anything I've told you and read further on your own. If you find something here that has changed, please tell me. I would rather correct it than have you rely on it.
- 1 Code of Virginia § 54.1-2132 — Licensees engaged by buyers Virginia General Assembly The statutory duties a buyer’s agent owes you, and the requirement to enter a brokerage agreement before showing property.
- 2 HB 1684 / SB 1309 (2025) — written agreement before showing Virginia REALTORS® legal update Repealed the prior exemption and defined “showing property.” Effective July 1, 2025.
- 3 Code of Virginia § 54.1-2139 — Disclosed dual agency Virginia General Assembly When one licensee may represent both sides, and the written consent required.
- 4 Code of Virginia § 54.1-2139.1 — Designated agency Virginia General Assembly Two agents in the same firm, each representing their own client.
- 5 Virginia Residential Property Disclosure Act, § 55.1-700 et seq. Virginia General Assembly What a Virginia seller must and need not disclose. The source of the “buyer beware” standard.
- 6 Lead-based paint disclosure — 42 U.S.C. § 4852d; 40 CFR Part 745 U.S. EPA / HUD Federal disclosure and pamphlet requirements for housing built before 1978.
- 7 A Citizen’s Guide to Radon U.S. Environmental Protection Agency Health risk, testing, and mitigation guidance.
- 8 Flood Map Service Center Federal Emergency Management Agency Official flood zone determination for any address.
- 9 Sex Offender and Crimes Against Minors Registry, § 9.1-900 et seq. Virginia State Police Searchable by address or radius.
- 10 Fair Housing Act, 42 U.S.C. § 3601 et seq. U.S. Dept. of Housing and Urban Development Why your agent provides sources rather than opinions about neighborhoods, schools, or who lives where.
- 11 Loan Estimate — 12 CFR § 1026.19(e) Consumer Financial Protection Bureau Form, timing, and how to compare lenders with it.
- 12 Closing Disclosure — 12 CFR § 1026.19(f) Consumer Financial Protection Bureau Must be delivered at least three business days before closing.
- 13 Homeowners Protection Act of 1998, 12 U.S.C. § 4901 et seq. U.S. Congress / CFPB Your right to have private mortgage insurance terminated.
- 14 Affiliated Business Arrangement disclosure — RESPA, 12 CFR § 1024.15 Consumer Financial Protection Bureau Requires written disclosure of a referral relationship, and that you are never required to use the referred provider.
- 15 Business Email Compromise and real estate wire fraud FBI Internet Crime Complaint Center Reported losses and the verification practice that prevents them.
- 16 Quarterly Indicators and Housing Supply Overview Richmond Association of REALTORS® / CVR MLS Source for list-to-sale ratio, days on market, months of supply, and median and average sale price in this market.
- 17 CVRMLS Area Map (form CVR 1100) Central Virginia Regional MLS The numbered MLS areas used in every Richmond-area listing and comparable sale.
- 18 Underground Utility Damage Prevention Act, § 56-265.15 et seq. Virginia 811 Required notification before any digging.
- 19 Address change requirements Virginia Department of Motor Vehicles Timeframe for updating your license and registration after a move.
- 20 Profile of Home Buyers and Sellers National Association of REALTORS® Annual national research on who buys, why they move, and how long they search.
- 21 Homebuyer loan and down payment assistance programs Virginia Housing Program eligibility and current terms for VHDA financing.
- 22 Real Estate Board regulations, 18VAC135-20 Virginia Dept. of Professional and Occupational Regulation Licensing, advertising, and disclosure rules governing every Virginia agent — including license lookup.
- 23 SpotCrime crime map SpotCrime Maps incidents reported by local police departments by address, with free alerts.
This guide is educational, not legal, tax, or lending advice. Statutes and regulations are current as of August 2026 and do change; market figures change constantly. For your specific transaction, your closing attorney, your lender, and your tax advisor are the authorities — and I am glad to bring any of them into the conversation.
Your agent
Kristin Beran Krupp
The Beran Group
Associate Broker · Partner & Owner
Licensed since 2004 · Top 1% of Realtors nationally
Questions are the whole point.
Before, during, or years after your purchase — call, text, or email. There is no such thing as bothering me.
Shaheen, Ruth, Martin & Fonville Real Estate
5808 Grove Avenue, Richmond, VA 23226 · 804.288.2100
 Shaheen, Ruth, Martin & Fonville Real Estate · 5808 Grove Avenue, Richmond, VA 23226 · 804.288.2100 · Equal Housing Opportunity